Rolex Watch Insurance: Costs, Providers & Coverage
How to protect your Rolex from theft, damage, and loss — with real premium data, provider comparisons, and a step-by-step claims guide.
Price context: this guide includes indicative insurance premiums and watch values from its original publication period. Confirm current quotes directly with each provider before purchasing a policy.
- Standard homeowners and renters policies cap jewelry claims at roughly $1,500 — nowhere near the value of a Rolex
- Specialty watch insurance typically costs 1–2% of the insured value per year ($100–$200 for a $10,000 watch)
- Top-rated providers include Hodinkee (Chubb), Jewelers Mutual, Zillion, BriteCo, and Lavalier
- Agreed-value policies lock in a guaranteed payout — no depreciation disputes at claim time
- A professional appraisal is recommended for pre-owned watches and required by most providers above $5,000–$10,000
Why Homeowners Insurance Falls Short
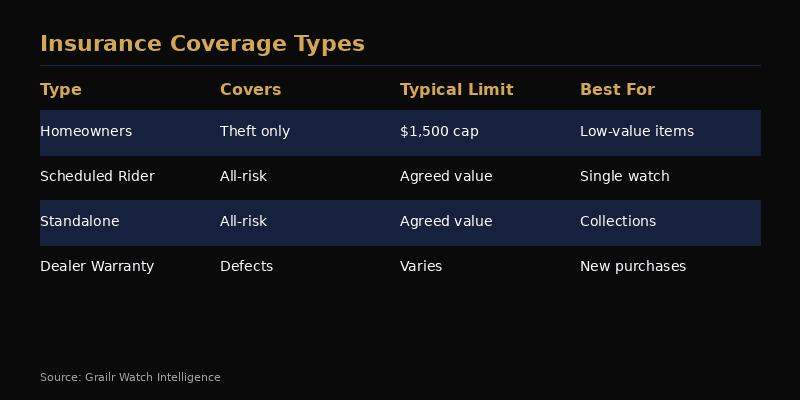
Many Rolex owners assume their watch is covered under a homeowners or renters policy. Technically, it is — but the coverage is almost certainly inadequate. Standard HO-3 homeowners policies cap “unscheduled” jewelry claims at approximately $1,500. Some policies set the limit even lower, at $1,000. That might replace a fashion watch. It will not replace a Submariner.
Even if your Rolex is stolen, the claim is subject to your standard homeowners deductible — often $1,000 or more — and the payout is based on depreciated value rather than replacement cost. Worse, homeowners policies typically do not cover mysterious disappearance (you set the watch down and it vanished), accidental damage (you knocked it off a table), or loss while traveling internationally.
You can add a “scheduled personal property” rider to your homeowners policy for a specific watch, which raises the coverage limit. But the premium is frequently higher than a standalone specialty policy, and the coverage is often narrower. That makes standalone watch insurance the better option for most Rolex owners — broader coverage, competitive pricing, and no impact on your homeowners claim history.
Coverage Types Explained
Watch insurance is not one-size-fits-all. There are three primary ways to insure a Rolex, each with different tradeoffs in coverage, cost, and claims experience.
1. Scheduled Rider on Homeowners/Renters Policy
You list the watch as a named item on your existing policy with its appraised value. Coverage limits are raised for that specific piece. The upside is a single policy and one billing relationship. The downsides: the premium often exceeds standalone options, coverage may exclude certain perils like accidental damage, and a claim could affect your homeowners premium at renewal.
2. Standalone Specialty Policy (Recommended)
A dedicated policy from a provider like Hodinkee, Jewelers Mutual, or Zillion that covers only your watches and jewelry. These policies are typically written on an agreed-value basis — the insured value is locked in at policy inception, so there is no depreciation argument at claim time. Most offer $0 deductible options, worldwide coverage, and coverage for mysterious disappearance. A standalone claim does not touch your homeowners policy.
3. Collector’s / Multi-Watch Policy
If you own three or more watches, some providers offer a blanket collector’s policy that covers the entire collection under one umbrella. This can simplify management and sometimes lower the per-watch premium. Jewelers Mutual and BriteCo both offer multi-item options with volume discounts.
| Feature | Homeowners Rider | Standalone Policy | Collector’s Policy |
|---|---|---|---|
| Agreed-value payout | Sometimes | Yes | Yes |
| $0 deductible option | Rare | Common | Common |
| Mysterious disappearance | Usually excluded | Typically included | Typically included |
| Worldwide travel | Varies | Yes | Yes |
| Affects home claim history | Yes | No | No |
| Best for | Single watch, simple setup | Most Rolex owners | 3+ watch collections |
Top Rolex Insurance Providers Compared
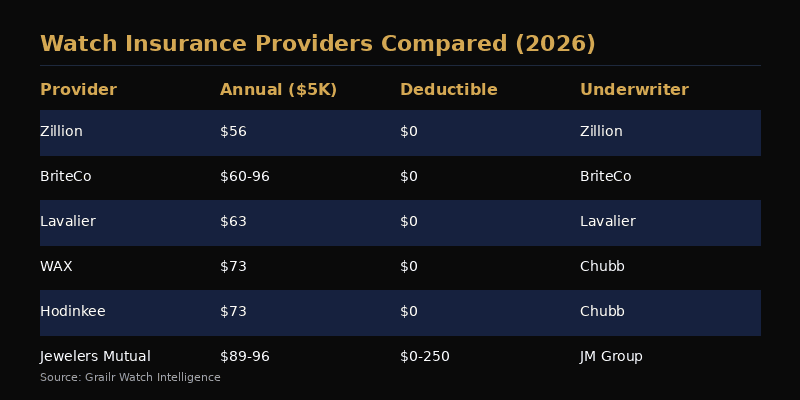
Not all watch insurance is equal. Some providers specialize exclusively in timepieces; others are jewelry-focused with watch options. Here is how the leading providers stack up at a $5,000 insured value — a representative benchmark since provider-quoted premiums vary by location, watch type, and personal factors.
| Provider | Annual Premium ($5K) | Deductible | Underwriter | Notable Feature |
|---|---|---|---|---|
| Zillion | ~$56/yr | $0 | Various A-rated | Lowest quoted premium |
| BriteCo | $60–$96/yr | $0 | Various A-rated | Appraisal included in some plans |
| Lavalier | ~$63/yr | $0 | Various A-rated | Fast online quoting |
| Hodinkee Insurance | ~$73/yr | $0 or $250 | Chubb | Pays cash; up to 150% if replacement costs more |
| WAX (Chubb) | ~$73/yr | $0 or $250 | Chubb | Backed by Chubb’s global claims network |
| Jewelers Mutual | $89–$96/yr | $0, $100, or $250 | Jewelers Mutual (direct) | Insuring jewelry since 1913; repair-first option |
A few provider-specific notes worth highlighting:
- Hodinkee only requires a formal appraisal for watches insured above $100,000. Below that threshold, a purchase receipt or existing documentation is typically sufficient. Claims are paid in cash, giving you the freedom to choose your own replacement.
- Hodinkee and WAX are both underwritten by Chubb, one of the world’s largest insurers. If claims experience matters to you, Chubb’s global network is hard to beat.
- Jewelers Mutual has been insuring jewelry and watches since 1913 — over a century of specialization. They offer a “repair first” option that can be more practical than cash settlement if your watch is damaged rather than lost.
All premiums above are indicative quotes at $5,000 insured value. Your actual rate depends on your location, the watch model, storage arrangements, and claims history. Always request a direct quote before purchasing.
What Does Rolex Insurance Cost?
The general rule: expect to pay 1–2% of the insured value per year for a standalone specialty policy. That percentage can drop below 1% with higher deductibles, multi-watch discounts, or a home safe. Here is what that looks like across different Rolex price points:
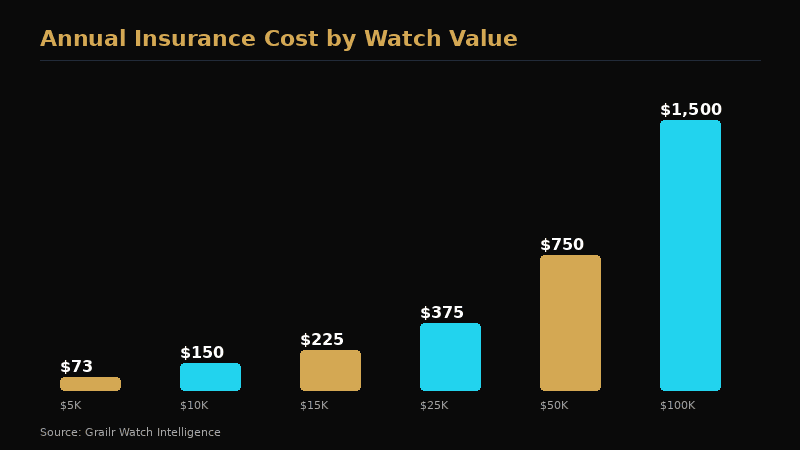
$10,000 Rolex
$100–$200/yr
Submariner Date, Explorer II, or pre-owned Datejust 41
$15,000 Rolex
$150–$300/yr
GMT-Master II, Yacht-Master 40, or newer Submariner
$25,000 Rolex
$250–$500/yr
Day-Date, Sky-Dweller, or ceramic Daytona
$50,000 Rolex
$500–$1,000/yr
Precious-metal Daytona, vintage Submariner, or Day-Date 40 in gold
To put that in perspective: insuring a $15,000 GMT-Master II costs roughly $12–$25 per month — less than most streaming subscriptions. If you’re not sure what your Rolex is currently worth, check our guide to Rolex valuation before requesting a quote. Insuring based on an outdated purchase price can leave you underinsured if the market has moved.
Deductible tradeoffs: choosing a $250 deductible instead of $0 can lower your annual premium by 15–25%. For a $10,000 watch, that might save $20–$40 per year. Whether the savings justify the out-of-pocket exposure on a claim depends on how risk-tolerant you are and how frequently you wear the watch in high-risk situations.
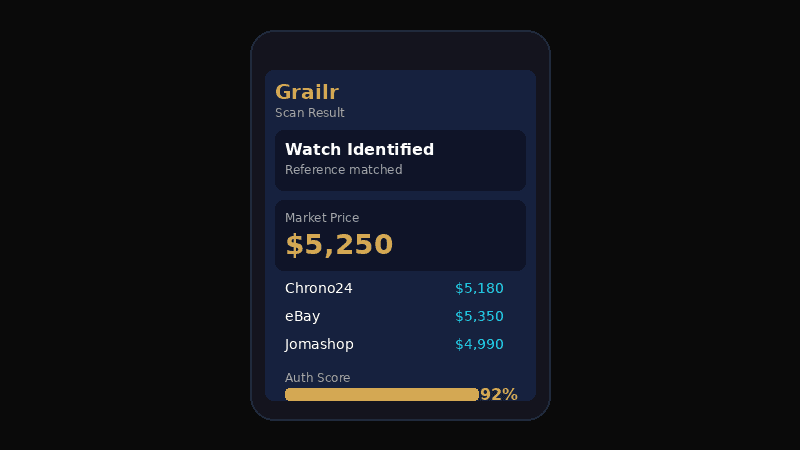
Check Any Watch Price in Seconds
Grailr scans your watch photo and pulls live pricing from Chrono24, eBay, and Jomashop.
- AI identifies brand, model & reference number
- Live market prices from 3+ sources
- Authentication confidence score
Appraisals and Documentation
Before you can insure a Rolex, you need to establish its value. The documentation requirements vary by provider and by the insured amount, but the general framework is straightforward.
For new watches purchased from an authorized dealer: the receipt is usually sufficient. It shows the reference number, serial number, purchase date, and the amount paid. Most providers accept this without requiring an additional appraisal.
For pre-owned watches: a professional appraisal is typically required for pieces valued above $5,000–$10,000. The appraisal should be conducted by a certified horological appraiser — not a jeweler who “also does watches.” Look for appraisers with ASA (American Society of Appraisers) or ISA (International Society of Appraisers) credentials. Expect to pay $50–$150 for a single-watch appraisal.
For high-value pieces: Hodinkee only requires a formal appraisal for watches insured above $100,000. Below that, existing documentation — receipts, prior appraisals, or dealer invoices — is typically accepted. Other providers set the threshold lower.
Regardless of provider requirements, having a current appraisal strengthens your position in any claim. Appraisals should be refreshed every 2–3 years, because Rolex secondary market values can shift meaningfully — an appraisal from 2022 may understate or overstate today’s replacement cost.
How to File a Watch Insurance Claim
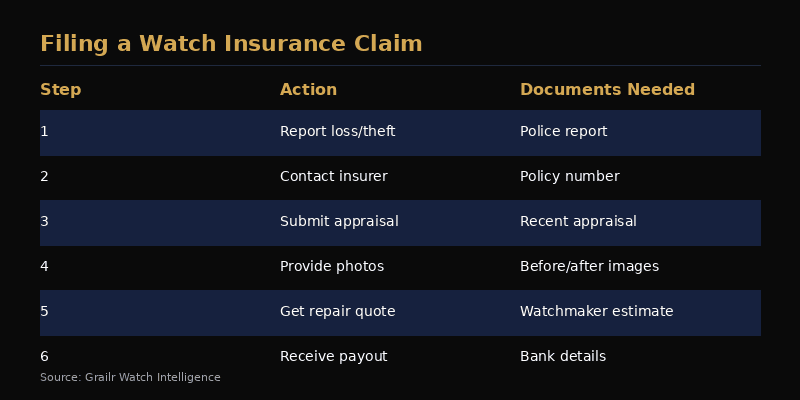
Nobody plans on filing a claim, but knowing the process before you need it makes the experience far less stressful. Here is what a typical watch insurance claim looks like, step by step.
Step 1: Report the Loss Immediately
Contact your insurer as soon as possible — most policies require notification within 24–72 hours. For theft, file a police report first; many providers require a report number before processing the claim. If the watch was lost while traveling, also contact the hotel, airline, or local authorities.
Step 2: Gather Your Documentation
Have these ready: your policy number, the most recent appraisal or purchase receipt, photographs of the watch (front, back, serial number), the police report number (for theft), and a written description of what happened. The more complete your file, the faster the process.
Step 3: Adjuster Review
The insurer assigns an adjuster who reviews your claim, documentation, and police report. For high-value claims (typically $25,000+), an independent investigation may be conducted. This is normal and not an indication of suspicion — it is a standard underwriting procedure for large payouts.
Step 4: Settlement
On an agreed-value policy, the payout is the insured amount minus any deductible. Hodinkee policies can pay up to 150% of the insured value if the replacement cost has risen since the policy started. Cash-settlement providers let you choose where to source the replacement; repair-first providers like Jewelers Mutual may coordinate the repair directly.
Typical turnaround from initial report to settlement is 2–6 weeks for straightforward claims. Theft claims involving international travel or high-value pieces can take longer due to investigation requirements. Keeping thorough records — serial number photos, warranty cards, authentication documentation — significantly accelerates the process.
Frequently Asked Questions
How much does Rolex watch insurance cost?
Most specialty watch insurance runs 1-2% of the insured value per year. A $10,000 Submariner costs roughly $100-200 annually; a $50,000 Daytona costs around $500-1,000. Standalone providers like Zillion and Lavalier often come in at the lower end of that range.
Does homeowners insurance cover a Rolex?
Standard homeowners and renters policies typically cap unscheduled jewelry claims at around $1,500 — well below the value of any Rolex. You can add a scheduled rider for a specific watch, but standalone specialty policies often provide broader coverage at a competitive price.
Do I need an appraisal to insure my Rolex?
It depends on the provider and the insured value. Hodinkee only requires a formal appraisal for watches insured above $100,000. Most providers accept a recent purchase receipt for new watches and may request an appraisal for pre-owned pieces valued above $5,000-$10,000.
What does watch insurance actually cover?
Specialty watch policies typically cover theft, accidental damage, mysterious disappearance, and worldwide travel. Some also cover damage during shipping. Most do not cover mechanical wear, cosmetic scratches, or losses from war or nuclear events.
What is agreed-value coverage for watches?
Agreed-value coverage locks in a payout amount when the policy begins. If your watch is insured for $15,000, you receive $15,000 in a covered total loss — no depreciation or market-value disputes at claim time. Hodinkee can even pay up to 150% if the replacement cost has risen.
Is Rolex insurance worth it?
For most owners, yes. At 1-2% of the watch's value per year, you are paying $100-200 annually to protect a $10,000 asset against theft, accidental damage, and loss. Without specialty coverage, your homeowners policy likely caps jewelry claims at $1,500.
Related Articles
The Bottom Line
A Rolex is one of the few personal items that can be worth more than a used car. Protecting it with a dedicated insurance policy is not optional — it is prudent ownership. At 1–2% of the watch’s value per year, the premium is trivial compared to the asset at risk. Start by getting quotes from two or three providers, choose an agreed-value policy with worldwide coverage, and keep your appraisal current. If your watch appreciates — as many Rolex models do — update the insured value so you are never caught underinsured.
Know Your Watch’s Value Before You Insure
Grailr technology identifies your watch from a photo and provides an indicative value estimate with live market data. Use it as a starting point before requesting an appraisal or insurance quote.
Scan a Watch NowSources and price context
- Chubb Valuables Coverage — Describes Chubb’s agreed-value personal article coverage, which underwrites both Hodinkee Insurance and WAX watch policies.
- Jewelers Mutual Jewelry Insurance — Outlines coverage options, deductible tiers, and claims processes from this century-old specialty insurer.
These primary sources support the provider and coverage details noted above. Premium figures are indicative editorial estimates based on published rate ranges and may vary by location, watch model, and individual risk profile. Confirm current quotes directly with each provider before purchasing a policy. Asking prices referenced for watch values are not completed-sale prices.